
First Home Buyers & Buying Strategy
Buying a House at Auction NZ: Pre-Approval, Bidding & Finance Rules
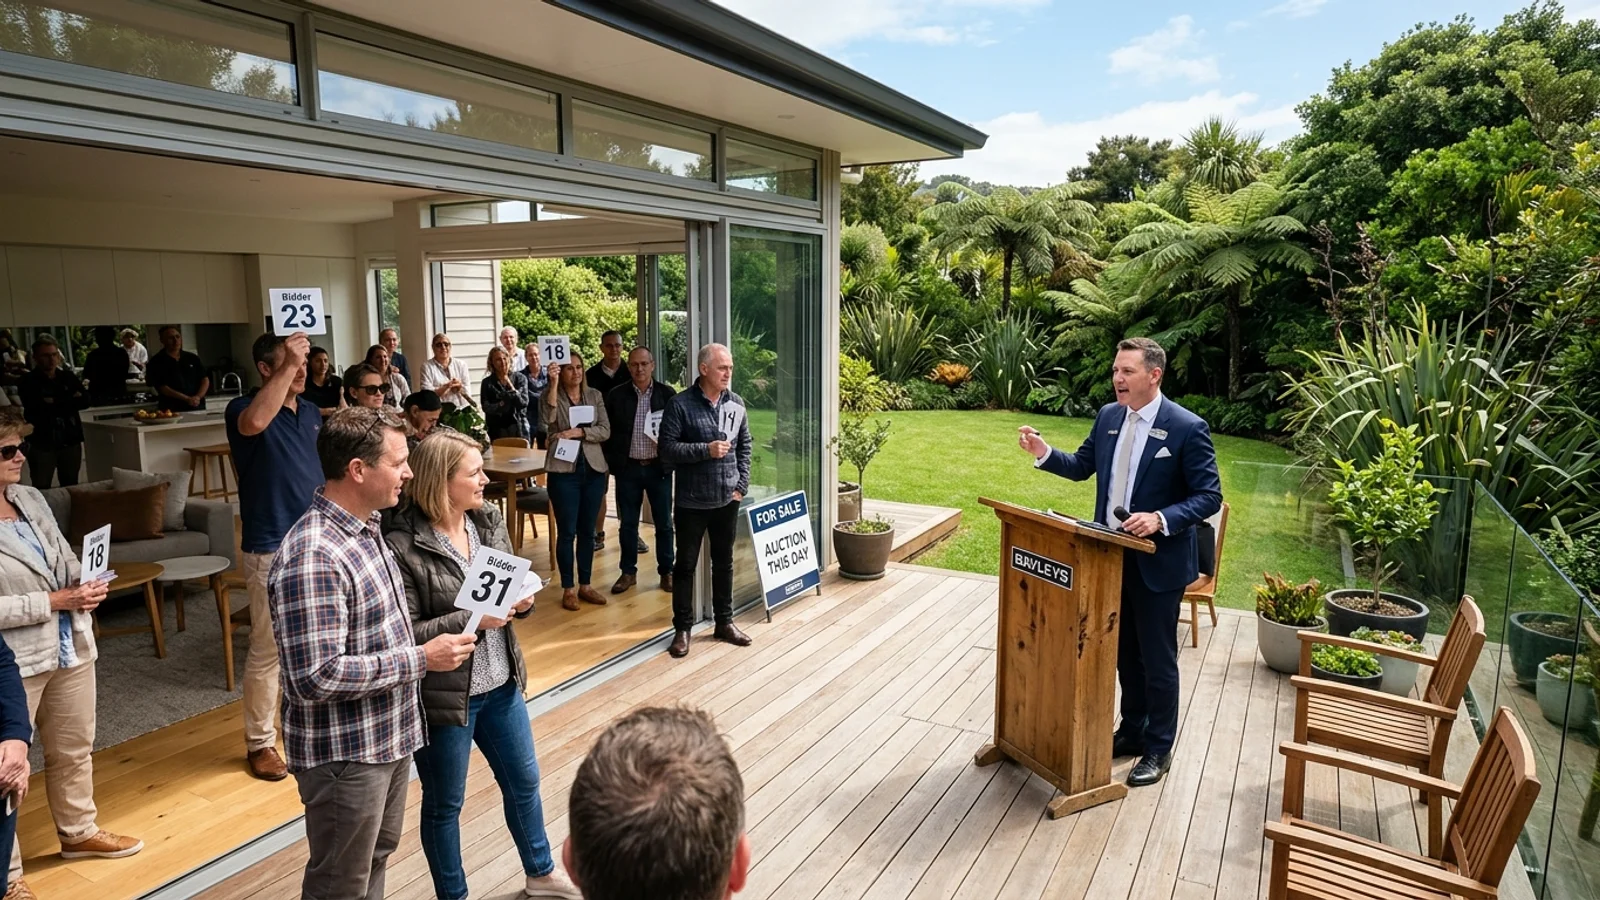
When the hammer falls at a New Zealand property auction, you have bought a house unconditionally. There is no cooling-off period, no subject-to-finance escape hatch, and certainly no taking the property back for store credit.
The straight answer: buying a house at auction in NZ requires property-specific bank approval and a cleared 10% deposit ready in your account on auction day.
Bidding at an auction with only a general pre-approval letter is a bolder gamble than my golf swing in a crosswind. A standard pre-approval confirms that the bank likes your income, but it says nothing about whether the bank will accept the specific property you are bidding on.
If you place the winning bid and your lender discovers unconsented alterations, a defective title, or a low registered valuation afterwards, you remain legally bound to settle. If you cannot produce the funds, you forfeit your deposit and face severe financial damages.
Here is how auction finance works in New Zealand, why you need property-specific sign-off, how to handle the 10% deposit, and the step-by-step due diligence required before raising your hand.
Why Auctions in NZ Are Completely Unconditional
In a standard private treaty sale in New Zealand, you can submit a conditional offer. You might include a 10-working-day finance condition, a satisfactory building report clause, and a solicitor's approval clause. If something goes wrong during that window, you can cancel the agreement without penalty.
An auction operates on the complete opposite premise.
Under rules set by the Real Estate Authority (REA) and detailed on Settled.govt.nz, bidding at an auction is an unconditional legal commitment.
The moment the auctioneer calls "sold" and strikes the podium:
- You have entered an immediate, legally binding agreement to purchase the property.
- You cannot insert a single conditional clause after the fact.
- You must sign the sale and purchase contract immediately.
- You must pay a 10% deposit on the spot.
If your finance falls over between auction day and settlement day, the seller is entitled to retain your full 10% deposit. If they subsequently resell the property for less than your winning bid, they can take legal action against you to recover the difference plus interest and costs.
The General Pre-Approval Trap: Why You Need Property-Specific Approval
The most dangerous misconception in New Zealand real estate is that a standard "pre-approval" letter gives you permission to bid at an auction.
It does not.
A standard pre-approval is conditional. It confirms that the lender is satisfied with your income, credit history, and general affordability. But it always contains a critical clause: "Subject to satisfactory property security."
(Yes, the real estate agent will tell you your pre-approval is "good as gold." No, they won't pay the shortfall if the bank rejects the property's unconsented deck on settlement day.)
To bid safely at an auction, your mortgage adviser must convert your general pre-approval into a property-specific unconditional approval before auction day.
This requires sending the property's particulars to the lender so their credit assessors can verify:
- The Title: Checking for restrictive covenants, cross-lease defects, unit title body corporate issues, or shared access easements.
- The Property Type: Ensuring the building complies with bank policy (e.g. plaster cladding, monolithic construction, or apartment floor-area minimums).
- The Valuation: Confirming whether the bank requires a full desktop valuation or registered valuation before you bid.
- Your Maximum Bid Cap: Establishing a hard, written lending limit for that specific address.
Learn more about getting your initial paperwork in order in our mortgage pre-approval guide.
The 10% Auction Deposit: Mechanics, Cleared Funds & KiwiSaver Traps
When you win an auction, you must pay the deposit immediately upon signing the contract. In New Zealand, the default auction deposit is 10% of the purchase price.
If you buy a home for $900,000, you need $90,000 transferred into the real estate agency's trust account that day.
The KiwiSaver Auction Trap
First home buyers frequently assume they can use their KiwiSaver balance to pay the auction day deposit.
In almost all cases, you cannot.
A KiwiSaver first home withdrawal takes 10 to 15 working days to process. Scheme providers pay the funds directly to your conveyancing solicitor's trust account to be held until settlement. They will not release funds on 10 minutes' notice to a real estate agency's auction room.
If your deposit is tied up in KiwiSaver or a gifted family contribution, you have two options:
Option A: Pre-Negotiate a Deposit Variation
Have your lawyer submit a formal variation to the vendor's solicitor before auction day. You can request to pay a smaller cash deposit on the day (e.g. $20,000 or 5%), with the balance payable upon KiwiSaver release. The vendor must agree in writing before the auction starts.
Option B: Use Cleared Cash Savings
Pay the 10% auction deposit from your everyday savings or a temporary family buffer. When your KiwiSaver funds settle later, the surplus funds will simply reduce your final loan drawdown at settlement.
Also remember to increase your daily bank transfer limits. Many New Zealand banks default to a $10,000 to $50,000 daily internet banking limit. If you need to transfer an $80,000 deposit from your phone after winning, call your bank beforehand to raise your limit.
Essential Due Diligence: LIM Reports, Title Searches & Building Checks
Because you cannot attach conditions to an auction bid, all your investigations must take place before you walk into the room.
This means spending money on due diligence for a property you might not even win. While paying for reports on multiple properties can feel frustrating, discovering structural rot or unconsented plumbing after the auction will cost tens of thousands more.
1. Independent Building Inspection
Engage an accredited building surveyor to inspect weathertightness, subfloor structures, roof condition, moisture readings, and unconsented works. Never rely on a vendor-supplied building report alone — an independent inspector works solely in your interest.
2. Council LIM (Land Information Memorandum)
Review the council records for zoning, flooding risks, overland flow paths, building consents, and Code Compliance Certificates (CCC). Unconsented alterations noted on a LIM can cause a lender to withdraw finance immediately.
3. Legal Review of Auction Terms
Send the "Particulars and Conditions of Sale" to your property solicitor. Your lawyer will check the Certificate of Title for encumbrances, restrictive covenants, or cross-lease defects, and verify settlement dates and chattels lists.
Read our full breakdown of buyer checks in our how to buy a house in NZ guide.
Registered Valuations & House Insurance Hurdles
Even if your personal finances and the property's LIM report are pristine, two critical roadblocks can derail auction finance: registered valuations and insurability.
1. Bank Valuation Requirements
If you are borrowing with less than a 20% deposit (a high-LVR loan) or buying in a rapidly fluctuating market, your lender will often require a registered valuation through an approved ordering portal (such as CoreLogic or Valocity) prior to auction.
The bank will only lend against the lesser of the registered valuation or the actual purchase price.
If the registered valuation comes back at $800,000, and you bid $850,000 at the auction, the bank will calculate your loan percentage based on $800,000. You will have to fund the entire $50,000 difference in cash from your own pocket.
2. Obtaining a Certificate of Currency (Insurance)
No New Zealand lender will release mortgage funds on settlement day without proof of full replacement house insurance (a Certificate of Currency).
Before bidding, contact an insurance provider with the property address. If the home is in a designated flood zone, landslip-prone area, or has historical earthquake damage that hasn't been properly signed off, insurers may decline cover or impose massive excesses.
No insurance means no loan drawdown — and an unconditional auction contract leaves you holding the bill.
Setting a Hard Bidding Limit: Avoiding the Emotional Overbid
Auctions are engineered by real estate agencies to create emotional urgency. Rapid-fire bidding, crowded rooms, and encouraging agents can easily tempt buyers into stretching "just one more bid."
I've done this since 2017, and watching an excited buyer bid past their approved bank limit still gives me more grey hair than my golf handicap.
Know your deposit and your numbers before the first call. A borrower who can say "I've got a 10% deposit ready in cleared funds, pre-approval up to $850,000, and my lawyer has approved the auction terms" gets taken seriously faster than someone guessing on the auction room floor.
Calculate your maximum borrowing parameters with our borrowing power calculator, and stick to your ceiling without exception.
If your lender has approved you to bid up to $820,000, that is your absolute ceiling. Bidding $825,000 means you must produce that extra $5,000 out of your own cash reserves on settlement day. If you don't have it, the bank will not simply top up your loan to cover an emotional bid.
What Happens If the Property Passes In?
If bidding does not reach the vendor's reserve price, the auctioneer will "pass the property in."
This is often the best outcome for cautious buyers.
Under standard auction protocols, the highest bidder is granted the first opportunity to negotiate directly with the vendor.
Once the auction process has concluded and negotiations open:
- Conditions Are Back on the Table: You can submit a standard conditional Sale and Purchase Agreement.
- Finance Clauses: You can include a 5-to-10-working-day finance condition, allowing your lender to conduct unhurried property checks.
- Building & Valuation Conditions: You can make the deal subject to a satisfactory valuation and building report.
If you are uncomfortable with the unconditional nature of an auction, waiting for the property to pass in and submitting a conditional offer immediately afterwards is a legitimate strategy.
Five Steps to Get Auction-Ready with an AML Adviser
Preparing for an auction requires speed, precision, and clear communication between your mortgage adviser, lawyer, and lender.
Real Auckland Scenario: The 5-Day Auction Turnaround
A couple in South Auckland found their ideal family home going to auction with just 5 working days before auction day. Their main bank told them it would take 10–15 working days just to assess the title and property documents. Kundan reviewed the file, ran the property through an appropriate lender on AML's panel, and secured full property-specific sign-off within 3 days. The couple attended the auction, stuck strictly to their bidding limit, and won under the hammer. The bank they had originally approached called back a week after the auction was already done.
Follow these five steps before auction day:
Get Pre-Approved
Secure pre-approval so you know your maximum borrowing capacity and deposit parameters.
Property Check
Send the property address, LIM, and auction terms to your adviser for lender sign-off.
Legal Review
Have your solicitor check the title and negotiate any deposit variations in writing.
Confirm Funds
Ensure your 10% deposit is sitting in cleared funds and raise your daily transfer limit.
Set Your Limit
Fix your maximum bid in writing, walk into the room, and do not exceed your number by a single dollar.
Get expert guidance for your purchase on our first home buyers page or get in touch with our team.
FAQs
Straight Answers: Buying at Auction in NZ
Can you buy a house at auction with standard pre-approval in NZ?
No. Standard pre-approval only confirms that the bank is happy with your personal income and borrowing capacity. It does not cover the property. For an auction, you must have property-specific approval in writing from your lender before you bid, confirming they accept the title, LIM, valuation, and building condition.
How much deposit do I need to pay on auction day in New Zealand?
The standard auction deposit in New Zealand is 10% of the purchase price, payable immediately upon signing the contract on auction day. If you need to pay a lower deposit (e.g., 5%), your solicitor must negotiate and submit an agreed variation with the vendor before the auction begins.
Can I use KiwiSaver to pay the 10% auction deposit on the day?
Generally, no. KiwiSaver first home withdrawals take 10 to 15 working days to be processed and paid into your solicitor's trust account. Because auction deposits are due on the day, you must fund the 10% deposit from cash savings, an agreed bridging buffer, or have your solicitor negotiate a delayed deposit clause prior to bidding.
What happens if I win an auction and my bank refuses to finance the property?
Auction contracts are completely unconditional. If you are the winning bidder and your lender declines finance, you remain legally contracted to settle. If you cannot settle, the vendor can cancel the contract, keep your 10% deposit, resell the home, and sue you for any resale price shortfall and legal costs.
What is property-specific pre-approval for an auction?
Property-specific approval occurs when your mortgage adviser sends the specific property's Certificate of Title, LIM report, auction agreement, and registered valuation (if required) to your lender for formal review. The lender signs off on the property before auction day, ensuring they will fund it up to your agreed maximum bid.
What happens if a property passes in at auction in NZ?
If bidding fails to reach the vendor's reserve price, the property "passes in." The highest bidder usually gets the first right to negotiate directly with the vendor. Once an auction passes in, you can introduce conditional clauses into your offer — such as a 5-working-day finance or building inspection condition.
Do I need a lawyer before bidding at an auction in NZ?
Yes. Because an auction contract is unconditional from the moment the hammer falls, your conveyancing solicitor must review the title search, auction terms, LIM report, and vendor disclosures before auction day to identify any restrictive covenants, easements, or legal risks.
Taking on an Auction in New Zealand?
If you are heading to an auction room this weekend, don't let the hammer do the deciding for you. Book a free consultation with Kundan Singh — we will get your finance signed, sealed, and ready to bid.
- Zero upfront fee for advice — we are typically remunerated directly by the lender upon settlement
- Access to 20 bank and non-bank lenders on our panel (7 banks, 13 non-bank)
- Property-specific sign-off — we check the title, valuation, and lender criteria before you bid
- Licensed Financial Advice Provider (FSP 714331 / Kundan Singh FSP 512966)
- Fast turnaround — reply within 2 business hours and pre-approvals in 3–5 business days