Home Loans
Home Loan Cash Back in NZ: What the Fine Print Actually Costs You

Photo: Gergely Mészárcsek / Pexels
A home loan cash back is a lump sum a lender pays you when your loan settles with them — a percentage of the loan or a flat dollar figure, sitting in your account within days of settlement. Free money is my favourite kind of money, right up until I read the clawback clause.
The straight answer: yes, it's real cash, and yes, it's yours. But nearly every cash back in NZ comes with strings attached for a set number of years, and those strings matter more than the number on the offer letter.
Before you chase the biggest figure on the table, it's worth understanding what you're actually agreeing to.
What Is a Home Loan Cash Back?
A cash back is money a lender pays you as an incentive to bring your mortgage to them — either a brand-new loan or a refinance from another bank. It's usually a percentage of your loan amount, sometimes a flat dollar figure, and the exact number moves with each lender's current promotion. It lands in your account after settlement, not before.
It's the lender paying it, not your adviser. A cash back doesn't reduce what an adviser gets paid, and at AML we don't invoice a client to arrange one — see how we're actually paid, below.
The catch isn't the cash. It's what happens if you leave before the lender's clawback period is up — and every lender runs one.
If the cash back is earmarked for a renovation rather than sitting in your account, our guide to home improvement loans in NZ covers how a top-up or cash-out refinance compares to spending the cash back itself.
How the Clawback Actually Works
A clawback clause means that if you repay the loan early — by refinancing to another lender, selling the property, or paying it off in full — within a set window after settlement, you have to repay some or all of the cash back.
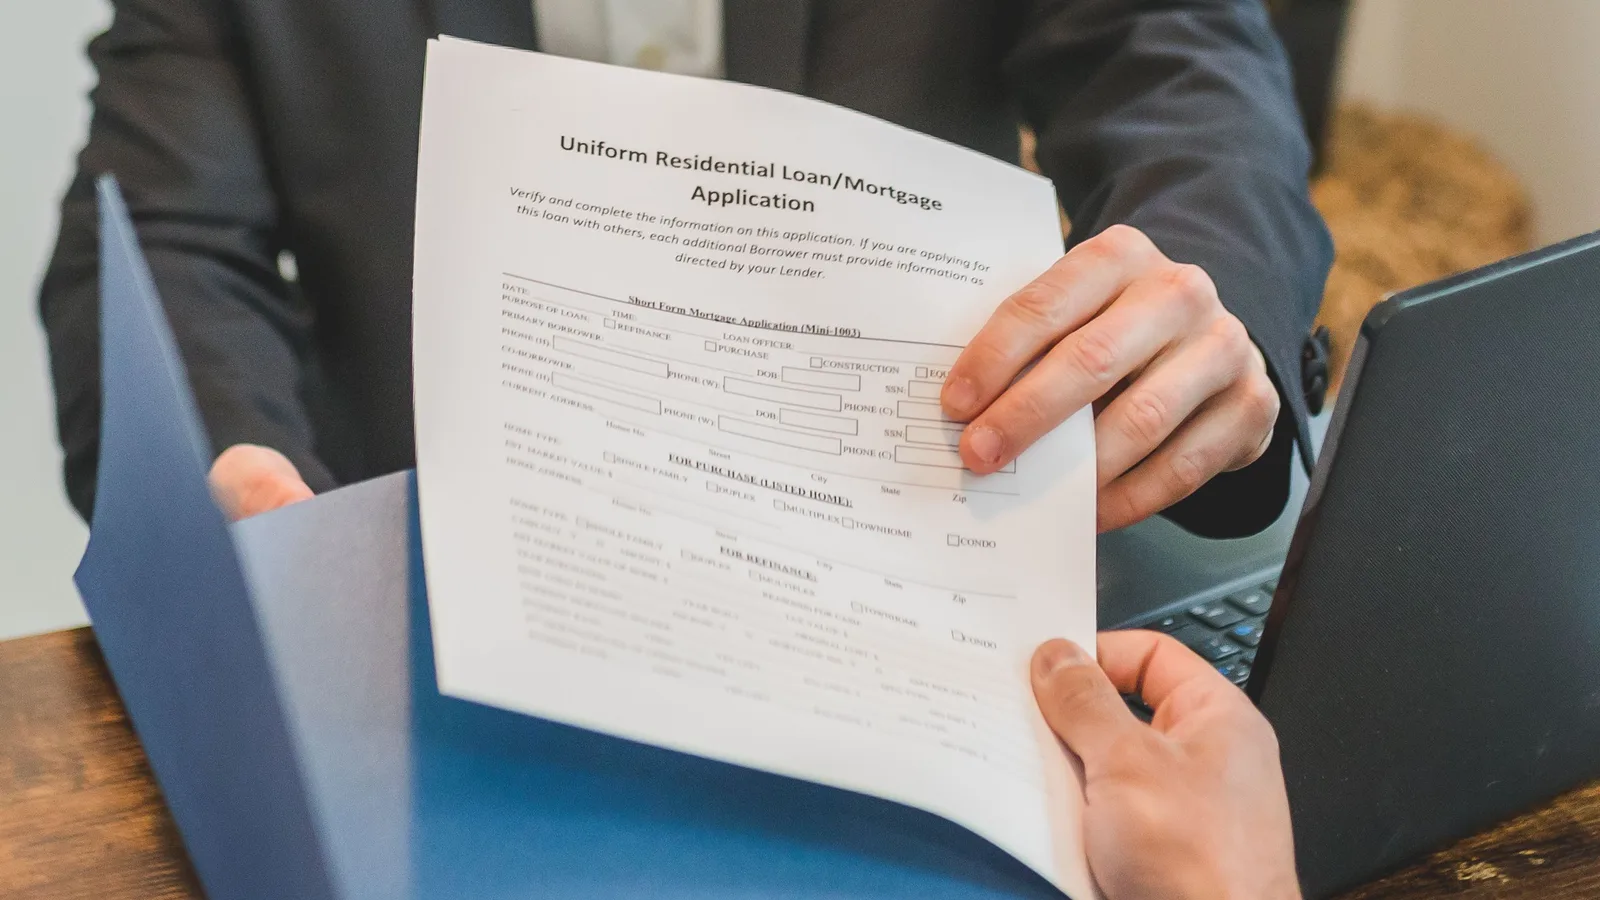
Every lender runs its own clawback period, and every lender calculates it differently. Some step the amount down each year until it reaches zero. Others hold the full amount liable right up until the clawback period ends, then drop it to nil. None of this sits on a rate card — it's in the letter of offer, in the fine print. A clawback does exactly what it says on the tin: the bank grows a claw, and it knows precisely where your cash back landed.
(Yes, the number in the letter of offer really is binding. No, "I didn't read that bit" doesn't get you out of it.)
Ask for the specific clawback terms on any offer before you accept it. If you can't get a straight answer to "how much would I owe if I refinanced in eighteen months," that's a warning sign, not a formality.
Why the Biggest Cash Back Isn't Always the Best Deal
Here's the opinion: the lowest rate on paper isn't always the cheapest loan once you price in cashback clawback, break fees, or a lender that won't flex later. A bigger cheque up front can end up costing more than it saves.
A larger cashback offer can come bundled with a longer clawback window, or a stricter serviceability policy than other lenders on the panel run. If your situation shifts even slightly before settlement — income, employment, or the property itself — a tighter policy is more likely to catch you out than a looser one would, and the cashback you were counting on can end up costing more than it's worth.
The lesson isn't "never take a cash back." It's this: read the clawback terms with the same attention you'd give the interest rate, because one of those numbers is designed to grab your attention and the other is designed not to.
Clawback vs Break Fee: Two Different Bills
A clawback and a break fee are not the same charge, and it's easy to confuse them when both can show up on the same settlement statement.
A break fee applies if you end a fixed interest rate term early. It's charged by whichever lender holds your mortgage right now, and it exists regardless of whether you ever took a cash back.
A clawback applies if you took a cash back and then leave the lender, sell, or repay early within that lender's clawback window. It's the incentive being reversed, in part or in full.
Switch banks mid-fixed-term after taking a cashback, and you can be looking at both bills on the same day. Neither one is optional, and neither shows up until you ask. If restructuring your existing loan — rather than switching lenders entirely — might sidestep one of these bills, our page on restructuring and refixing is worth a look first.
Is a Cash Back Worth Taking?
Cash back isn't automatically good or bad. It depends on what you're likely to do with the loan over the clawback period.
Staying put for the long haul?
A cash back is close to free money — take it, and keep a note of the clawback terms in case your plans change.
Planning to sell or refinance within a few years?
Run the numbers before you accept. The clawback could outweigh the cash you're being offered.
Comparing two offers with different cashback amounts?
Compare total cost over your expected time in the loan — not just the figure on the cheque. Our mortgage calculators are a starting point for running the repayment side of that comparison.
Already mid-way through a clawback period with your current bank?
Ask what refinancing would actually cost before you assume switching is worth it. Sometimes it still is — sometimes the maths says wait.
If you're comparing a cash back against refinancing to a genuinely lower rate elsewhere, our guide to refinancing an existing home loan walks through the full process.
How AML Compares Offers Across the Panel
This is where an adviser earns their keep — not by finding the biggest cheque, but by reading every offer's clawback terms, serviceability policy, and rate against your actual plans. I've read enough letters of offer to know the fine print is where lenders keep the interesting bits.
AML has 20 banks and non-bank lenders on panel — 7 banks, 13 non-bank — plus non-panel access to institutional and sophisticated investors. We compare cash back offers across all of them against your situation, not just whichever one your existing bank is pushing this month.
We reply within 2 business hours, and pre-approval is typically available in as little as 3–5 business days once your documents are ready. A cash back doesn't change our fee: financial advisers are required to disclose who pays them, and in the typical case, the lender pays AML once your loan settles — not you.
AML has settled 200+ home loans since 2017. We're a licensed Financial Advice Provider — AML Financial Services Limited, FSP 714331. Kundan Singh, FSP 512966. Both are on the Financial Service Providers Register — public record, worth checking for any adviser you speak with.
A cash back is a nice bit of theatre — the bank hands you money with one hand while the clawback clause waits in the other. Call us before you sign, and we'll tell you which hand to watch.