DTI Ratio NZ Home Loan: Rules, Caps & Non-Bank Exemptions
The Straight Answer on DTI Ratios in New Zealand
Borrowing six times your annual income sounds like plenty of money until you price an entry-level Auckland townhouse—at that point, six times your income can feel tighter than a pair of golf shoes two sizes too small. In New Zealand, the Debt-to-Income (DTI) ratio is a macroprudential ceiling enforced by the Reserve Bank of New Zealand (RBNZ). Since 1 July 2024, registered retail banks are restricted to lending a maximum of 6 times gross annual income for owner-occupiers and 7 times gross annual income for property investors. But here is what the banks rarely mention: DTI rules legally apply only to registered banks. Non-bank lenders, new residential builds, and refinancing existing debt carry explicit exemptions. If a bank declines your loan because of DTI limits, the deal is often still completely fundable.
1. What Is the Debt-to-Income (DTI) Ratio in New Zealand?
For years, New Zealand home lending was governed almost entirely by Loan-to-Value Ratios (LVR)—the size of your cash deposit compared to the purchase price. If you had a 20% deposit (or a 10% deposit with a low equity margin), the bank looked at whether your weekly pay could cover mortgage payments at a test interest rate.
On 1 July 2024, the Reserve Bank changed the playing field by introducing mandatory Debt-to-Income restrictions. While LVR protects banks against falling house prices by ensuring you have equity in the property, DTI restrictions are designed to prevent borrowers from taking on unsustainable debt multiples regardless of how much deposit they have.
Simply put, your DTI is a multiplier. If your household earns $120,000 before tax and your total debt is $600,000, your DTI ratio is 5.0. If your debt reaches $720,000 on that same income, you hit a DTI of 6.0.
The critical difference is that DTI does not care about your spending habits, whether you buy brand-name coffee, or whether you have a pristine credit score. It is a mathematical ceiling set by the central bank.
2. How Banks Calculate Your DTI: Debt vs Income Breakdown
The basic formula looks straightforward:
Where borrowers get tripped up is how underwriters define "debt" and "income." The bank does not just count the new mortgage you are asking for.
What Counts as "Total Debt"?
Under RBNZ rules, retail banks must tally every single form of debt linked to your name:
- The New Mortgage: The total loan balance you are applying to borrow.
- Existing Mortgages: Any mortgages you currently hold on other homes, baches, or rentals.
- Personal & Car Loans: Vehicle financing, hire purchase, personal bank loans, and boat loans.
- Student Loans: Your outstanding IRD student loan balance.
- Credit Card & Overdraft Limits: This is the single biggest trap. Underwriters count the full approved limit of your credit cards, store cards, and overdraft facilities—even if your card balance is $0.
(Yes, that means if you have an unused $10,000 credit card in your wallet "just for emergencies," the bank logs it as $10,000 of active debt. You're welcome.)
What Counts as "Gross Income"?
Income is calculated on gross (pre-tax) earnings, but banks apply strict haircuts depending on how the income is earned:
- Base PAYE Salary: 100% of proven base salary or regular contracted hours.
- Overtime, Bonuses & Commissions: Usually shaded to 75% or 80%, requiring a 12-to-24 month proven track record.
- Self-Employed Profits: Based on the most recent 1 to 2 years of accountant-prepared financial statements (see our guide to self-employed home loans in NZ).
- Residential Rental Income: Heavily shaded by mainstream banks, typically discounted to 65%–75% of gross rent to account for rates, insurance, maintenance, and vacancies.
- Boarder Income: Capped by lender policy (usually max $150 to $200 per week per boarder, subject to IRD standard cost rules).
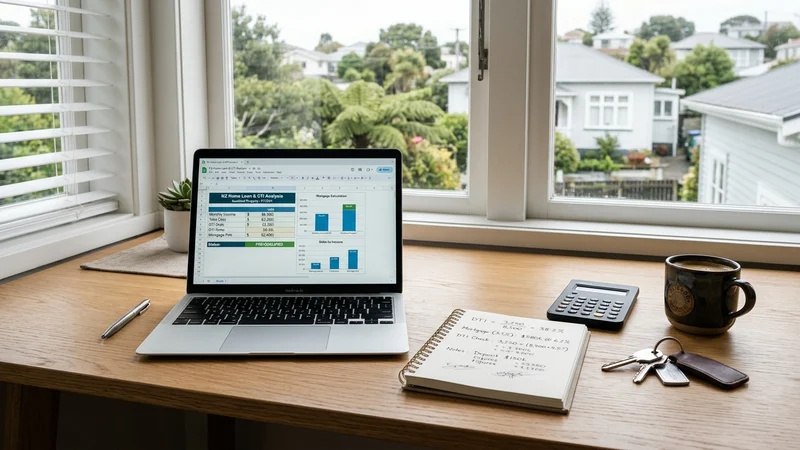
Calculating your true DTI requires adding all existing debt commitments and credit limits to your proposed mortgage.
3. RBNZ DTI Restrictions: 6x and 7x Caps Explained
The RBNZ framework splits borrowers into two distinct categories: owner-occupiers (people buying a home to live in) and property investors.
| Borrower Category | Standard DTI Cap | High-DTI "Speed Limit" Allowance | Key Criteria |
|---|---|---|---|
| Owner-Occupiers | DTI of 6.0 | Up to 20% of new lending volume | Primary residence, First Home Buyers, upgraders |
| Residential Property Investors | DTI of 7.0 | Up to 20% of new lending volume | Rental properties, multiple investment titles |
Why Banks Hoard Their 20% Speed Limit
You might look at that 20% allowance and think: "Great, if my DTI is 6.2, the bank can just put me in their 20% high-DTI bucket."
In practice, banks are very stingy with those speed limits. If a bank breaches the 20% cap over a reporting quarter, they face severe regulatory penalties from the Reserve Bank. As a result, banks hoard that 20% allowance for their highest-margin clients, private banking customers, or low-LVR buyers with massive cash buffers.
I've been in financial advice since 2017, and watching a branch underwriter decline a solid, hardworking Kiwi family simply because the bank's internal quarterly speed-limit bucket is full for the month never gets any less frustrating.
4. DTI vs LVR vs Bank Servicing: The Three Mortgage Ceilings
When applying for a home loan in New Zealand, your borrowing capacity is dictated by whichever of three separate ceilings is the lowest. As we detail in our guide on how much can I borrow for a home loan in NZ, you must pass all three:
LVR Restriction
Dictates the loan amount relative to property value. Typically requires a 10%–20% deposit for owner-occupiers, or 35% deposit for standard existing investment property.
Servicing Stress Test
Tests if your net take-home income can comfortably pay repayments at a test interest rate (e.g. 8.00%–8.50%) after deducting real living costs and commitments.
RBNZ DTI Cap
Caps total debt at 6x gross annual income (7x for investors). Even if you have zero living costs and a 50% deposit, registered banks cannot exceed this ratio.
In a high-interest-rate market, servicing calculations are often the primary constraint. But as interest rates trend down, your serviceability borrowing capacity expands rapidly—at which point the DTI cap becomes the hard brick wall stopping you from borrowing more from retail banks.
5. Exemptions: Who Can Borrow Over the DTI Cap?
The Reserve Bank recognised that a blanket debt multiple could stifle housing construction or trap existing mortgage holders. As a result, several key lending categories are formally exempt from DTI rules:
1. New Residential Builds
To keep the construction pipeline moving and stimulate housing supply, qualifying new builds are exempt from DTI rules. This applies to:
- Purchases off-the-plans directly from a developer (see buying off the plans in NZ).
- Properties purchased within six months of receiving their Code Compliance Certificate (CCC).
- Turnkey building contracts and progressive drawdown construction loans (see construction loan process in NZ).
2. Dollar-for-Dollar Refinancing
If your mortgage already sits at a DTI of 6.5 and you want to switch banks to get a sharper interest rate or restructure your loan tranches, the RBNZ allows an exemption. As long as you are refinancing an existing loan balance without borrowing fresh money, the new bank does not have to count your deal against their 20% speed-limit allowance.
3. Kāinga Ora First Home Loans
Lending underwritten by the government-backed Kāinga Ora First Home Loan scheme (which allows eligible first home buyers to purchase with a 5% deposit) has special carve-outs under macroprudential guidelines.
4. Bridging Finance
Short-term bridging loans (typically 6 to 12 months) used while you sell an existing home are exempt from standard long-term DTI calculations, provided there is an unconditional or credible sale strategy in place.
6. The Non-Bank Advantage: Lending Outside RBNZ Rules
Here is the single biggest fact that retail bank staff will never explain to you: RBNZ DTI regulations apply strictly to registered banks.
Non-bank lenders and specialist mortgage institutions are not registered banks. They are non-bank deposit takers and wholesale-funded non-bank institutions. Under New Zealand law, they are not bound by the RBNZ's DTI speed limits.
At AML Home Loans, we have 20 bank and non-bank lenders on our panel (including 7 major retail banks and 13 non-bank lenders like Pepper Money, Liberty, Avanti Finance, Basecorp Finance, and First Mortgage Trust).
Banks decline good home loan applications on policy checklists, not merit. A deal gets a "no" because it doesn't fit a standardised box—an applicant whose income sits at 6.4x DTI, a self-employed business owner with strong cash flow but fluctuating tax accounts, or an investor with multiple rental streams—not because the numbers don't work.
Non-bank lenders look at real commonsense serviceability. If your actual surplus income comfortably handles mortgage payments, a non-bank lender can approve lending at DTIs of 7.0, 7.5, or higher for owner-occupiers.
The Strategy: A non-bank loan does not have to be forever. We frequently place clients who hit bank DTI restrictions with a non-bank lender to secure the property. Over the next 18 to 24 months, as their income rises, secondary debts are cleared, or property value increases, we refinance them back to a mainstream bank at standard rates.
7. 4 Steps to Improve Your DTI Before Applying
If you are preparing to buy a home or refinance in New Zealand and want to ensure your DTI sails through bank underwriting, here is the exact 4-step action plan we run with our clients:
Step 1: Cancel Unused Credit Cards & Overdrafts
If you have a credit card with a $15,000 limit that you rarely use, that card alone consumes $15,000 of your total allowable debt under DTI. Cancelling that card or reducing the limit down to $1,000 instantly expands your mortgage borrowing capacity by $14,000. Do this at least 30 days before applying so it reflects on your credit file.
Step 2: Clear Personal Loans & Buy Now Pay Later (BNPL)
Car finance, hire purchases, and Afterpay/Zip commitments add directly to your debt pile. Pay off small car loans or consolidate short-term debt before submitting your mortgage application (see our guide on what underwriters check in bank statements).
Step 3: Document Every Dollar of Secondary Income
Because DTI divides debt by total gross income, increasing your recognised income lowers your DTI ratio. Ensure your employer confirms recurring overtime, regular bonuses, and travel allowances in your formal employment letter. If you have boarders or flatmates, draft formal boarder agreements adhering to IRD criteria.
Step 4: Use an Adviser Who Has Access to the Full Panel
If you walk into a single bank branch and your DTI measures 6.1, that branch manager has one option: say no if their high-DTI quota is exhausted. An independent adviser can compare policies across 20 lenders to place your application with an institution that has available speed-limit capacity or with a non-bank lender that bypasses DTI restrictions entirely.
Straight Answers
Frequently Asked Questions About DTI in New Zealand
What is the maximum debt-to-income (DTI) ratio in New Zealand?
Under Reserve Bank of New Zealand (RBNZ) rules introduced in July 2024, the standard DTI cap for registered banks is 6 times gross annual income for owner-occupiers and 7 times gross annual income for residential property investors. Banks are allowed a 20% speed limit allowance to lend above these caps to borrowers with strong servicing profiles.
Do non-bank lenders in NZ have to follow RBNZ DTI caps?
No. RBNZ macroprudential DTI restrictions legally apply only to registered banks (such as ANZ, ASB, BNZ, Westpac, and Kiwibank). Non-bank and specialist lenders are not bound by RBNZ DTI speed limits. They assess affordability on actual cash flow and real mortgage serviceability rather than a rigid multiple of income.
Are new builds exempt from DTI restrictions in NZ?
Yes. To encourage housing supply, the RBNZ exempts qualifying residential new builds and turnkey construction contracts from DTI caps at registered banks. If you are purchasing off-the-plans or building a new home, banks do not have to count your loan against their high-DTI quota.
Why do unused credit card limits hurt your DTI ratio?
When calculating your total debt, banks include the total approved credit limit of all credit cards, store cards, and overdrafts—even if your balance is zero. A $10,000 credit card limit is treated as $10,000 of debt, which directly eats into your borrowing capacity under DTI rules.
What is the difference between DTI and bank servicing calculations?
DTI is a macro cap based purely on a multiple of your gross pre-tax income (Debt ÷ Income). Servicing is a separate cashflow stress-test where the bank assesses your net take-home pay against actual living expenses and tests mortgage repayments at an elevated interest rate (typically 8% or higher). You must pass both tests to get bank approval.
Can you refinance an existing mortgage if your DTI is over 6 or 7?
Yes. The RBNZ allows an exemption for dollar-for-dollar refinancing of existing residential debt. As long as you are not increasing your total loan amount or borrowing extra funds, switching your existing mortgage to a new bank does not count against their high-DTI quota.
The Bottom Line on DTI
The Reserve Bank’s DTI caps are designed to protect the financial system, not help you buy your dream home. But an arbitrary number on a central bank spreadsheet does not define your borrowing future. If your bank said no because their DTI speed limit bucket is full for the month, don't ask the same bank twice. Give us a call at AML Home Loans—we'll place your application with a lender who looks at what you can actually afford.
Hit a Bank DTI Wall? Let's Find the Right Lender.
We compare policies across 20 bank and non-bank lenders to find the approval that fits your real income.
- Free, no-obligation consultation
- Access to multiple banks and lenders
- Licensed Financial Advice Provider (FSP 714331)